October 15, 2026
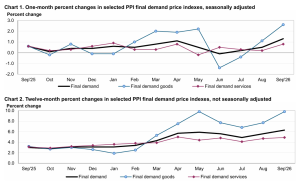
According to the U.S. Bureau of Labor Statistics, the Producer Price Index (PPI) for final demand increased 1.3% in September 2026, seasonally adjusted, following gains of 0.5% in August and 0.2% in July. This was the largest monthly increase since March 2022. On an unadjusted basis, the index for final demand rose 6.3% over the 12 months ended September 2026, the highest annual increase since December 2022.
The September increase was driven by broad-based gains in both goods and services. Prices for final demand goods advanced 2.6%, while final demand services increased 0.8%.
Excluding foods, energy, and trade services, the PPI for final demand increased 0.5% in September, following a 0.3% rise in August. Over the past year, this core measure advanced 5.0%.
Final demand goods
Prices for final demand goods increased 2.6% in September, the largest increase since the series began in 2009. More than 80% of the advance was attributable to a 10.8% increase in energy prices. Food prices rose 1.2%, while prices for goods excluding foods and energy increased 0.3%.
A significant contributor to the increase was a 20.3% surge in gasoline prices, which accounted for roughly half of the overall rise in final demand goods. Prices also increased for diesel fuel, fresh and dry vegetables, jet fuel, residential electric power, and crude petroleum. Offsetting these gains, prices for chicken eggs declined 39.7%, while thermoplastic resins and materials and commercial electric power also moved lower.
Final demand services
The index for final demand services increased 0.8%, matching the largest monthly gain since April 2026. Nearly half of the increase was attributable to a 1.4% rise in trade services margins. Transportation and warehousing services increased 3.4%, while services excluding trade, transportation, and warehousing advanced 0.3%.
A 3.9% increase in machinery and vehicle wholesaling margins was a major contributor to the rise in services prices. Additional gains were recorded in truck transportation of freight, food and alcohol wholesaling, traveler accommodation services, food retailing, and airline passenger services. Partially offsetting these increases, margins for automotive fuels and lubricants retailing fell 30.3%, while prices for securities brokerage, dealing and investment advice, and chemicals and allied products wholesaling also declined.
Disclaimer:
Analyst Certification – The views expressed in this research report accurately reflect the personal views of Mayberry Investments Limited Research Department about those issuer (s) or securities as at the date of this report. Each research analyst (s) also certify that no part of their compensation was, is, or will be, directly or indirectly, related to the specific recommendation(s) or view (s) expressed by that research analyst in this research report.
Company Disclosure – The information contained herein has been obtained from sources believed to be reliable, however its accuracy and completeness cannot be guaranteed. You are hereby notified that any disclosure, copying, distribution or taking any action in reliance on the contents of this information is strictly prohibited and may be unlawful. Mayberry may effect transactions or have positions in securities mentioned herein. In addition, employees of Mayberry may have positions and effect transactions in the securities mentioned herein.