November 13, 2026
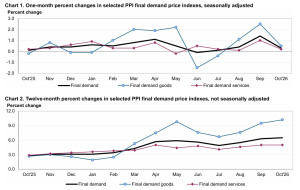
According to the U.S. Bureau of Labor Statistics, the Producer Price Index (PPI) for final demand increased 0.3% in October 2026, seasonally adjusted, following increases of 1.4% in September and 0.4% in August. On an unadjusted basis, the index for final demand rose 6.5% over the 12 months ended October 2026, marking the largest annual increase since November 2022.
The October increase was driven by advances in both goods and services. Prices for final demand goods rose 0.5%, while final demand services increased 0.2%.
Excluding foods, energy, and trade services, the PPI for final demand increased 0.5% in October, matching the gain recorded in September. Over the 12 months ended October 2026, this core measure advanced 4.9%.
Final demand goods
Prices for final demand goods increased 0.5% in October, following a 2.5% increase in September. More than 60% of the October advance was attributable to a 0.5% increase in goods excluding foods and energy. Food prices rose 1.3%, while energy prices edged down 0.1%. Over the past 12 months, the index for final demand goods advanced 10.2%, the largest annual increase since October 2022.
Among individual components, prices for basic organic chemicals increased 3.9%. Prices also rose for fresh and dry vegetables, gas fuels, aeronautical, nautical and navigational instruments, jet fuel, and processed young chickens. Offsetting these gains, diesel fuel prices declined 7.9%, while prices for pork and passenger cars also decreased.
Final demand services
The index for final demand services increased 0.2% in October, marking its fifth consecutive monthly increase. Approximately three-fourths of the advance was attributable to a 2.0% increase in transportation and warehousing services. Services excluding trade, transportation, and warehousing rose 0.2%, while margins for trade services declined 0.2%.
A 3.9% increase in truck transportation of freight accounted for more than 80% of the overall gain in final demand services. Transportation-related cost pressures therefore remained a significant contributor to producer inflation during the month, even as trade service margins softened.
Disclaimer:
Analyst Certification – The views expressed in this research report accurately reflect the personal views of Mayberry Investments Limited Research Department about those issuer (s) or securities as at the date of this report. Each research analyst (s) also certify that no part of their compensation was, is, or will be, directly or indirectly, related to the specific recommendation(s) or view (s) expressed by that research analyst in this research report.
Company Disclosure – The information contained herein has been obtained from sources believed to be reliable, however its accuracy and completeness cannot be guaranteed. You are hereby notified that any disclosure, copying, distribution or taking any action in reliance on the contents of this information is strictly prohibited and may be unlawful. Mayberry may effect transactions or have positions in securities mentioned herein. In addition, employees of Mayberry may have positions and effect transactions in the securities mentioned herein.